We use cookies to understand how you use our site and to improve your experience.
This includes personalizing content and advertising.
By pressing "Accept All" or closing out of this banner, you consent to the use of all cookies and similar technologies and the sharing of information they collect with third parties.
You can reject marketing cookies by pressing "Deny Optional," but we still use essential, performance, and functional cookies.
In addition, whether you "Accept All," Deny Optional," click the X or otherwise continue to use the site, you accept our Privacy Policy and Terms of Service, revised from time to time.
You are being directed to ZacksTrade, a division of LBMZ Securities and licensed broker-dealer. ZacksTrade and Zacks.com are separate companies. The web link between the two companies is not a solicitation or offer to invest in a particular security or type of security. ZacksTrade does not endorse or adopt any particular investment strategy, any analyst opinion/rating/report or any approach to evaluating individual securities.
If you wish to go to ZacksTrade, click OK. If you do not, click Cancel.
MP's Operating Losses Continue in Q2: Can It Revert to Profitability?
Read MoreHide Full Article
Key Takeaways
MP Materials narrowed its Q2 operating loss to $32 million, extending its loss streak to 12 quarters.
Revenues surged 89% as higher NdPr oxide and metal sales combined with stronger pricing.
Rising costs and downstream investments may keep near-term profitability under pressure despite higher output.
MP Materials Corp. (MP - Free Report) reported an operating loss of $32 million in the second quarter of 2026 compared with the year-ago loss of $43.9 million. Despite the narrower loss, the company extended its streak of operating losses to 12 consecutive quarters, reflecting ongoing margin pressure as it continues transitioning toward higher-value separated rare earth products.
During the quarter, revenues surged 89% year over year, fueled by higher neodymium-praseodymium (NdPr oxide) and metal sales and stronger pricing. However, cost of sales climbed 43% due to higher sales volumes of NdPr oxide and metal. Selling, general and administrative expenses rose 28% due to increased personnel costs. Start-up costs surged to $14 million from $0.76 million in the year-ago quarter due to the ramp-up of start-up activities for magnet production and chlor-alkali facilities, and costs associated with initial production of magnets at Independence.
This cost escalation trend has been building as MP accelerated its shift toward separated rare earth production. These products carry higher per-unit costs than rare earth concentrates because of the additional processing involved. Key cost components include chemical reagents, labor, maintenance and other consumables. In 2024, the cost of sales nearly doubled year over year to $192.6 million. In 2025, the cost of sales remained elevated at $192.8 million.
Operating expenses also trended higher. SG&A expenses rose 5% in 2024 and surged a further 35% in 2025, driven by workforce expansion to support downstream growth initiatives. MP Materials thus reported an operating loss of $169 million in 2024 and $149.4 million in 2025.
Producing separated rare earth products and magnetic materials involves significantly higher costs than concentrate production due to additional processing requirements, chemical inputs, labor and maintenance. Cost of sales is thus expected to trend higher, reflecting increased sales of NdPr oxide and metal along with added costs associated with magnetic precursor products. Start-up costs are also likely to increase in the coming quarters.
At the same time, NdPr production volumes continue to rise as process optimization and ramp-up efforts progress. Higher output, increased sales volumes and the United States Department of War’s (DoW) Price Protection Agreement will offset some of the margin pressure.
How Are MP’s Peers Faring?
Energy Fuels (UUUU - Free Report) reported an operating loss of $30.6 million in the second quarter of 2026 compared with a loss of $26.2 million in the year-ago quarter. Energy Fuels reported a 192% surge in its cost of sales. Total operating costs and expenses increased 83% year over year to $55.7 million in the second quarter of 2026. Energy Fuels has reported an adjusted operating loss in the last nine consecutive quarters.
USA Rare Earth Inc. (USAR - Free Report) reported early-stage revenues of $5.8 million in the second quarter of 2026, generated entirely from its Less Common Metals acquisition completed in 2025. It has not yet begun meaningful revenue generation from magnet manufacturing or mineral production. Meanwhile, total operating expenses surged 408% year over year. Selling, general and administrative increased 424%, due to higher legal and consulting costs and increased headcount. Operating loss in the quarter was $46.3 million compared with $8.8 million in the year-ago quarter.
MP’s Price Performance, Valuation & Estimates
MP Materials’ shares have declined 32.1% in a year against the industry’s 36.3% growth.
Image Source: Zacks Investment Research
MP is trading at a forward 12-month price/sales multiple of 12.77X, a significant premium to the industry’s 1.43X.
Image Source: Zacks Investment Research
The Zacks Consensus Estimate for MP Materials’ 2026 earnings is pegged at eight cents per share, indicating a solid improvement from the loss of 24 cents in 2025. The estimate for 2027 is 88 cents per share, indicating a 1,009% year-over-year improvement.
Image Source: Zacks Investment Research
The estimate for both years has moved down in the past 60 days.
Image Source: Zacks Investment Research
The company currently carries a Zacks Rank #5 (Strong Sell).



 View the Zacks #1 Rank List


Image: Shutterstock
MP's Operating Losses Continue in Q2: Can It Revert to Profitability?
Key Takeaways
MP Materials Corp. (MP - Free Report) reported an operating loss of $32 million in the second quarter of 2026 compared with the year-ago loss of $43.9 million. Despite the narrower loss, the company extended its streak of operating losses to 12 consecutive quarters, reflecting ongoing margin pressure as it continues transitioning toward higher-value separated rare earth products.
During the quarter, revenues surged 89% year over year, fueled by higher neodymium-praseodymium (NdPr oxide) and metal sales and stronger pricing. However, cost of sales climbed 43% due to higher sales volumes of NdPr oxide and metal. Selling, general and administrative expenses rose 28% due to increased personnel costs. Start-up costs surged to $14 million from $0.76 million in the year-ago quarter due to the ramp-up of start-up activities for magnet production and chlor-alkali facilities, and costs associated with initial production of magnets at Independence.
This cost escalation trend has been building as MP accelerated its shift toward separated rare earth production. These products carry higher per-unit costs than rare earth concentrates because of the additional processing involved. Key cost components include chemical reagents, labor, maintenance and other consumables. In 2024, the cost of sales nearly doubled year over year to $192.6 million. In 2025, the cost of sales remained elevated at $192.8 million.
Operating expenses also trended higher. SG&A expenses rose 5% in 2024 and surged a further 35% in 2025, driven by workforce expansion to support downstream growth initiatives. MP Materials thus reported an operating loss of $169 million in 2024 and $149.4 million in 2025.
Producing separated rare earth products and magnetic materials involves significantly higher costs than concentrate production due to additional processing requirements, chemical inputs, labor and maintenance. Cost of sales is thus expected to trend higher, reflecting increased sales of NdPr oxide and metal along with added costs associated with magnetic precursor products. Start-up costs are also likely to increase in the coming quarters.
At the same time, NdPr production volumes continue to rise as process optimization and ramp-up efforts progress. Higher output, increased sales volumes and the United States Department of War’s (DoW) Price Protection Agreement will offset some of the margin pressure.
How Are MP’s Peers Faring?
Energy Fuels (UUUU - Free Report) reported an operating loss of $30.6 million in the second quarter of 2026 compared with a loss of $26.2 million in the year-ago quarter. Energy Fuels reported a 192% surge in its cost of sales. Total operating costs and expenses increased 83% year over year to $55.7 million in the second quarter of 2026. Energy Fuels has reported an adjusted operating loss in the last nine consecutive quarters.
USA Rare Earth Inc. (USAR - Free Report) reported early-stage revenues of $5.8 million in the second quarter of 2026, generated entirely from its Less Common Metals acquisition completed in 2025. It has not yet begun meaningful revenue generation from magnet manufacturing or mineral production. Meanwhile, total operating expenses surged 408% year over year. Selling, general and administrative increased 424%, due to higher legal and consulting costs and increased headcount. Operating loss in the quarter was $46.3 million compared with $8.8 million in the year-ago quarter.
MP’s Price Performance, Valuation & Estimates
MP Materials’ shares have declined 32.1% in a year against the industry’s 36.3% growth.
Image Source: Zacks Investment Research
MP is trading at a forward 12-month price/sales multiple of 12.77X, a significant premium to the industry’s 1.43X.
Image Source: Zacks Investment Research
The Zacks Consensus Estimate for MP Materials’ 2026 earnings is pegged at eight cents per share, indicating a solid improvement from the loss of 24 cents in 2025. The estimate for 2027 is 88 cents per share, indicating a 1,009% year-over-year improvement.
Image Source: Zacks Investment Research
The estimate for both years has moved down in the past 60 days.
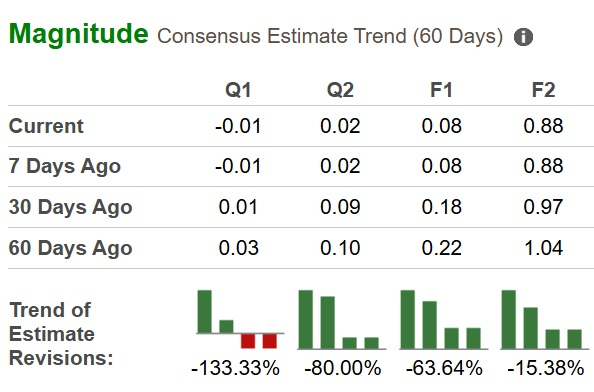
Image Source: Zacks Investment Research
The company currently carries a Zacks Rank #5 (Strong Sell).
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.