We use cookies to understand how you use our site and to improve your experience.
This includes personalizing content and advertising.
By pressing "Accept All" or closing out of this banner, you consent to the use of all cookies and similar technologies and the sharing of information they collect with third parties.
You can reject marketing cookies by pressing "Deny Optional," but we still use essential, performance, and functional cookies.
In addition, whether you "Accept All," Deny Optional," click the X or otherwise continue to use the site, you accept our Privacy Policy and Terms of Service, revised from time to time.
You are being directed to ZacksTrade, a division of LBMZ Securities and licensed broker-dealer. ZacksTrade and Zacks.com are separate companies. The web link between the two companies is not a solicitation or offer to invest in a particular security or type of security. ZacksTrade does not endorse or adopt any particular investment strategy, any analyst opinion/rating/report or any approach to evaluating individual securities.
If you wish to go to ZacksTrade, click OK. If you do not, click Cancel.
CAT Falls Below 50-Day SMA: Is It Time to Hold or Exit the Stock?
Read MoreHide Full Article
Key Takeaways
Caterpillar fell below its 50-day SMA after shares dropped 6% amid broader market and industry pressures.
Caterpillar posted a record $72B backlog and 24% revenue growth, with adjusted EPS up 73% year over year.
CAT raised its 2026 sales outlook, while acquisitions and services expansion support longer-term growth.
Caterpillar Inc. (CAT - Free Report) has fallen below its 50-day simple moving average (SMA), a widely used technical indicator used to assess near-term price trends and identify potential support or resistance levels. The stock dipped 6% to close at $813.83 yesterday, below its 50-day SMA of $821.99, raising questions about whether the recent weakness signals a deeper pullback or a potential buying opportunity.
CAT Stock Falls Below 50-Day Moving Average
Image Source: Zacks Investment Research
The decline comes amid broader pressure on U.S. equities as the 10-year Treasury yield surged to 5.368%, its highest level since early 2002. Machinery stocks also faced additional uncertainty after the Federal Trade Commission (FTC) and the U.S. Department of Agriculture (USDA) announced a joint inquiry and requested public comments on agricultural-equipment manufacturing and distribution practices. Although the probe focuses on farm machinery makers such as Deere & Company (DE - Free Report) rather than Caterpillar’s core markets, it has added to the cautious sentiment across the machinery space.
Despite the recent pullback, Caterpillar shares have gained 62.7% in the past year, outperforming the industry's 58.5% growth. It has also outpaced the 18.5% advance in the Zacks Industrial Products sector and the S&P 500’s 18.1% return. CAT has also delivered stronger returns than competitors, Deere, Komatsu (KMTUY - Free Report) and Terex Corp. (TEX - Free Report) , as shown in the chart below.
Image Source: Zacks Investment Research
Let’s examine the company’s strengths and weaknesses to better analyze how to play CAT stock in this situation.
Caterpillar’s Record Backlog Supports Revenue Visibility
Caterpillar generated $20.5 billion in second-quarter 2026 revenues, up 24% year over year. Growth was fueled by a $3.1 billion rise in sales volume across its business segments. Sales exceeded the $20 billion mark for the first time in the company’s history.
The company ended the second quarter of 2026 with a record backlog of $72 billion, 92% higher than last year. Backlog increased across all three segments, reflecting broad-based demand strength throughout the company’s portfolio. Around 59% of this backlog is expected to be delivered over the next 12 months. This percentage has remained relatively stable over the past three quarters, highlighting the strength and consistency of demand.
Cost of sales climbed 18% year over year due to higher manufacturing expenses, including tariff-related impacts. Selling, general and administrative expenses, and research and development expenses increased 19% and 12%, respectively. Despite higher expenses, adjusted operating margin expanded to 21.9% from 17.4% in the year-ago quarter, as higher volumes and pricing more than offset these pressures. Caterpillar reported adjusted earnings of $8.17 per share for the second quarter of 2026, up 73% year over year.
Caterpillar Expects Higher Revenues in 2026, Costs to Hurt
Caterpillar expects 2026 sales and revenues to increase in the mid-to-high teens, up from its previous low-double-digit growth forecast. The revised outlook reflects healthy demand across all three primary segments.
Tariffs will continue to affect Caterpillar’s manufacturing costs and segment margins. Adjusted operating margin is projected near the bottom of its target range. Caterpillar maintains an adjusted operating margin outlook of 15–19% at revenue levels of around $60 billion. If revenues reach $72 billion, operating margins are expected to be 18–22%, while revenues of $100 billion could support margins in the range of 21–25%.
Full-year Machinery, Power & Energy (MP&E) free cash flow is expected to land in the upper half of the company’s $6-$15 billion target range.
CAT’s Rising Estimates Signal Improving Profitability
The Zacks Consensus Estimate for 2026 points to year-over-year earnings growth of 44.1%, while the 2027 estimate implies growth of 20.9%, reflecting improving confidence in the company’s earnings trajectory.
Image Source: Zacks Investment Research
Earnings estimates for CAT have moved up for both 2026 and 2027 over the past 60 days.
Image Source: Zacks Investment Research
CAT Trades at a Premium Valuation
CAT is currently trading at a forward 12-month P/E of 25.67X, a premium compared with the industry’s 25.13X.
Image Source: Zacks Investment Research
Meanwhile, Komatsu and Terex are cheaper options, trading at a forward 12-month P/E of 17.51X and 9.51X, respectively. Deere is trading higher at 28.66X.
CAT Delivers Strong Returns on Capital
Caterpillar’s return on equity (ROE) is 55.53%, higher than the industry’s average of 53.33%. It is also higher than the S&P 500’s return of 38.46%. Meanwhile, Komatsu offers an ROE of 10.51% and Terex an ROE of 12.24%.
Caterpillar is positioned to benefit from several secular growth trends, including U.S. infrastructure spending, mining demand related to the energy transition, automation adoption, data center expansion and sustainability investments. The company plans to restart production of its 10-megawatt gas engine platform, targeting about 1.5 gigawatts of capacity, with shipments expected to begin in the fourth quarter. CAT is also expanding turbine capacity and investing in services, e-commerce, electrification, sustainability and digital technologies. Its services business is another important growth driver, with service revenues targeted to rise from $24 billion in 2025 to $30 billion by 2030.
Caterpillar is also using acquisitions to expand its dealer network and technology capabilities. The planned acquisition of John Fabick Tractor Company will strengthen its aftermarket presence, while its acquisitions of RPMGlobal and Skycatch are enhancing its mining software, automation and spatial-data capabilities.
How Should Investors Approach CAT Stock Now?
Caterpillar continues to post strong financial results, supported by robust revenue and earnings growth, a record backlog and rising earnings estimates. Its exposure to infrastructure development, mining, data centers and power generation provides additional long-term growth opportunities, while the expanding services business should contribute to more recurring, higher-margin revenues.
Overall, the break below the 50-day SMA signals near-term caution rather than a fundamental shift in Caterpillar’s outlook. Given the company’s strong growth outlook but relatively elevated valuation, investors may want to hold CAT stock and wait for a more attractive entry point. The company currently has a Zacks Rank #3 (Hold), which supports our thesis.



 View the Zacks #1 Rank List


Image: Bigstock
CAT Falls Below 50-Day SMA: Is It Time to Hold or Exit the Stock?
Key Takeaways
Caterpillar Inc. (CAT - Free Report) has fallen below its 50-day simple moving average (SMA), a widely used technical indicator used to assess near-term price trends and identify potential support or resistance levels. The stock dipped 6% to close at $813.83 yesterday, below its 50-day SMA of $821.99, raising questions about whether the recent weakness signals a deeper pullback or a potential buying opportunity.
CAT Stock Falls Below 50-Day Moving Average
Image Source: Zacks Investment Research
The decline comes amid broader pressure on U.S. equities as the 10-year Treasury yield surged to 5.368%, its highest level since early 2002. Machinery stocks also faced additional uncertainty after the Federal Trade Commission (FTC) and the U.S. Department of Agriculture (USDA) announced a joint inquiry and requested public comments on agricultural-equipment manufacturing and distribution practices. Although the probe focuses on farm machinery makers such as Deere & Company (DE - Free Report) rather than Caterpillar’s core markets, it has added to the cautious sentiment across the machinery space.
Despite the recent pullback, Caterpillar shares have gained 62.7% in the past year, outperforming the industry's 58.5% growth. It has also outpaced the 18.5% advance in the Zacks Industrial Products sector and the S&P 500’s 18.1% return. CAT has also delivered stronger returns than competitors, Deere, Komatsu (KMTUY - Free Report) and Terex Corp. (TEX - Free Report) , as shown in the chart below.
Image Source: Zacks Investment Research
Let’s examine the company’s strengths and weaknesses to better analyze how to play CAT stock in this situation.
Caterpillar’s Record Backlog Supports Revenue Visibility
Caterpillar generated $20.5 billion in second-quarter 2026 revenues, up 24% year over year. Growth was fueled by a $3.1 billion rise in sales volume across its business segments. Sales exceeded the $20 billion mark for the first time in the company’s history.
The company ended the second quarter of 2026 with a record backlog of $72 billion, 92% higher than last year. Backlog increased across all three segments, reflecting broad-based demand strength throughout the company’s portfolio. Around 59% of this backlog is expected to be delivered over the next 12 months. This percentage has remained relatively stable over the past three quarters, highlighting the strength and consistency of demand.
CAT Demonstrates Earnings Momentum Despite Higher Costs
Cost of sales climbed 18% year over year due to higher manufacturing expenses, including tariff-related impacts. Selling, general and administrative expenses, and research and development expenses increased 19% and 12%, respectively.
Despite higher expenses, adjusted operating margin expanded to 21.9% from 17.4% in the year-ago quarter, as higher volumes and pricing more than offset these pressures. Caterpillar reported adjusted earnings of $8.17 per share for the second quarter of 2026, up 73% year over year.
Caterpillar Expects Higher Revenues in 2026, Costs to Hurt
Caterpillar expects 2026 sales and revenues to increase in the mid-to-high teens, up from its previous low-double-digit growth forecast. The revised outlook reflects healthy demand across all three primary segments.
Tariffs will continue to affect Caterpillar’s manufacturing costs and segment margins. Adjusted operating margin is projected near the bottom of its target range. Caterpillar maintains an adjusted operating margin outlook of 15–19% at revenue levels of around $60 billion. If revenues reach $72 billion, operating margins are expected to be 18–22%, while revenues of $100 billion could support margins in the range of 21–25%.
Full-year Machinery, Power & Energy (MP&E) free cash flow is expected to land in the upper half of the company’s $6-$15 billion target range.
CAT’s Rising Estimates Signal Improving Profitability
The Zacks Consensus Estimate for 2026 points to year-over-year earnings growth of 44.1%, while the 2027 estimate implies growth of 20.9%, reflecting improving confidence in the company’s earnings trajectory.
Image Source: Zacks Investment Research
Earnings estimates for CAT have moved up for both 2026 and 2027 over the past 60 days.
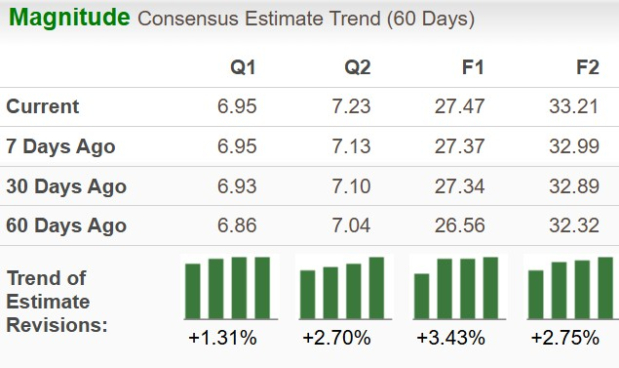
Image Source: Zacks Investment Research
CAT Trades at a Premium Valuation
CAT is currently trading at a forward 12-month P/E of 25.67X, a premium compared with the industry’s 25.13X.
Image Source: Zacks Investment Research
Meanwhile, Komatsu and Terex are cheaper options, trading at a forward 12-month P/E of 17.51X and 9.51X, respectively. Deere is trading higher at 28.66X.
CAT Delivers Strong Returns on Capital
Caterpillar’s return on equity (ROE) is 55.53%, higher than the industry’s average of 53.33%. It is also higher than the S&P 500’s return of 38.46%. Meanwhile, Komatsu offers an ROE of 10.51% and Terex an ROE of 12.24%.
Image Source: Zacks Investment Research
Caterpillar’s Long-Term Growth Drivers Remain Intact
Caterpillar is positioned to benefit from several secular growth trends, including U.S. infrastructure spending, mining demand related to the energy transition, automation adoption, data center expansion and sustainability investments.
The company plans to restart production of its 10-megawatt gas engine platform, targeting about 1.5 gigawatts of capacity, with shipments expected to begin in the fourth quarter. CAT is also expanding turbine capacity and investing in services, e-commerce, electrification, sustainability and digital technologies. Its services business is another important growth driver, with service revenues targeted to rise from $24 billion in 2025 to $30 billion by 2030.
Caterpillar is also using acquisitions to expand its dealer network and technology capabilities. The planned acquisition of John Fabick Tractor Company will strengthen its aftermarket presence, while its acquisitions of RPMGlobal and Skycatch are enhancing its mining software, automation and spatial-data capabilities.
How Should Investors Approach CAT Stock Now?
Caterpillar continues to post strong financial results, supported by robust revenue and earnings growth, a record backlog and rising earnings estimates. Its exposure to infrastructure development, mining, data centers and power generation provides additional long-term growth opportunities, while the expanding services business should contribute to more recurring, higher-margin revenues.
Overall, the break below the 50-day SMA signals near-term caution rather than a fundamental shift in Caterpillar’s outlook. Given the company’s strong growth outlook but relatively elevated valuation, investors may want to hold CAT stock and wait for a more attractive entry point. The company currently has a Zacks Rank #3 (Hold), which supports our thesis.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.