We use cookies to understand how you use our site and to improve your experience.
This includes personalizing content and advertising.
By pressing "Accept All" or closing out of this banner, you consent to the use of all cookies and similar technologies and the sharing of information they collect with third parties.
You can reject marketing cookies by pressing "Deny Optional," but we still use essential, performance, and functional cookies.
In addition, whether you "Accept All," Deny Optional," click the X or otherwise continue to use the site, you accept our Privacy Policy and Terms of Service, revised from time to time.
You are being directed to ZacksTrade, a division of LBMZ Securities and licensed broker-dealer. ZacksTrade and Zacks.com are separate companies. The web link between the two companies is not a solicitation or offer to invest in a particular security or type of security. ZacksTrade does not endorse or adopt any particular investment strategy, any analyst opinion/rating/report or any approach to evaluating individual securities.
If you wish to go to ZacksTrade, click OK. If you do not, click Cancel.
How Mission Produce Plans to Bounce Back From a Tough Quarter
Read MoreHide Full Article
Key Takeaways
AVO targets a profitability rebound after Q3 margin pressures despite solid revenue growth.
Higher Peruvian avocado sales, blueberry gains and Calavo benefits should lift AVO's Q4 adjusted EBITDA.
AVO expects Calavo cost synergies to grow in fiscal 2027, but pricing pressures and debt remain risks.
Mission Produce, Inc. (AVO - Free Report) is focusing on operational efficiency, sourcing flexibility and strategic integration to strengthen profitability following a challenging third quarter of fiscal 2026. Despite solid revenue growth, lower avocado selling prices, acquisition-related expenses and weaker International Farming profitability pressured margins. However, resilient distribution performance and better-than-expected farming returns provided some relief. Management remains focused on translating strong avocado demand and expanding market reach into sustainable earnings growth while maintaining pricing discipline.
A major component of Mission Produce's recovery strategy involves leveraging its diversified sourcing network and improving agricultural productivity. Greater avocado availability from California and Peru has enhanced supply flexibility, allowing the company to better align fruit sizes and sourcing origins with customer demand. Stronger Peruvian production and the seasonal ramp-up in blueberry operations are expected to support profitability in the coming quarters. Meanwhile, the Calavo acquisition expands Mission Produce's customer relationships, packing capabilities and distribution infrastructure. Management is pursuing cost synergies through network optimization, procurement efficiencies and reduced external sourcing expenses, with benefits expected to become increasingly meaningful in fiscal 2027.
Looking ahead, Mission Produce anticipates a significant sequential improvement in fourth-quarter adjusted EBITDA, supported by higher Peruvian avocado sales, stronger blueberry contributions and a full-quarter benefit from Calavo. Improving avocado margin dynamics and integration-related savings should provide additional support. Moreover, rising avocado consumption and growing retail penetration offer opportunities to expand market share. Nevertheless, persistent pricing pressures, integration costs and elevated debt remain concerns. The company's ability to execute operational improvements, generate stronger cash flow and realize acquisition synergies will be crucial to sustaining its recovery momentum.
How Are Other Agribusiness Players Driving a Recovery?
Corteva, Inc. (CTVA - Free Report) and Dole plc (DOLE - Free Report) are pursuing strategic initiatives to navigate industry challenges and strengthen profitability.
Corteva is focusing on innovation, operational efficiency and portfolio optimization to strengthen profitability amid persistent agricultural market challenges. Following the separation of its seed business, Vylor, Corteva is positioned as a more focused crop protection company, emphasizing differentiated products, biological solutions and improved cost competitiveness. Demand for newer crop protection technologies and ongoing productivity initiatives could support its recovery despite competitive pricing pressures, particularly in Latin America.
Dole is prioritizing operational resilience, portfolio optimization and financial flexibility to navigate a challenging fresh produce environment. Although higher fuel and shipping costs, unfavorable weather conditions and supply disruptions have pressured its Fresh Fruit operations, strength across its diversified fresh produce businesses continues to provide support. The company's recent divestiture of its Ecuadorian port business has strengthened its balance sheet, creating greater flexibility for strategic investments and debt reduction.
AVO’s Price Performance, Valuation & Estimates
Shares of Mission Produce have lost 7.7% in the last three months compared with the industry’s decline of 27%.
Image Source: Zacks Investment Research
From a valuation standpoint, AVO trades at a forward price-to-earnings ratio of 14.44X, above the industry’s average of 14.69X. Image Source: Zacks Investment Research
The Zacks Consensus Estimate for AVO’s fiscal 2026 earnings suggests a year-over-year decline of 17.7%, while that for fiscal 2027 indicates growth of 33.8%. The company’s EPS estimates for fiscal 2026 and 2027 have remained stable in the past seven days.



 View the Zacks #1 Rank List


Image: Bigstock
How Mission Produce Plans to Bounce Back From a Tough Quarter
Key Takeaways
Mission Produce, Inc. (AVO - Free Report) is focusing on operational efficiency, sourcing flexibility and strategic integration to strengthen profitability following a challenging third quarter of fiscal 2026. Despite solid revenue growth, lower avocado selling prices, acquisition-related expenses and weaker International Farming profitability pressured margins. However, resilient distribution performance and better-than-expected farming returns provided some relief. Management remains focused on translating strong avocado demand and expanding market reach into sustainable earnings growth while maintaining pricing discipline.
A major component of Mission Produce's recovery strategy involves leveraging its diversified sourcing network and improving agricultural productivity. Greater avocado availability from California and Peru has enhanced supply flexibility, allowing the company to better align fruit sizes and sourcing origins with customer demand. Stronger Peruvian production and the seasonal ramp-up in blueberry operations are expected to support profitability in the coming quarters. Meanwhile, the Calavo acquisition expands Mission Produce's customer relationships, packing capabilities and distribution infrastructure. Management is pursuing cost synergies through network optimization, procurement efficiencies and reduced external sourcing expenses, with benefits expected to become increasingly meaningful in fiscal 2027.
Looking ahead, Mission Produce anticipates a significant sequential improvement in fourth-quarter adjusted EBITDA, supported by higher Peruvian avocado sales, stronger blueberry contributions and a full-quarter benefit from Calavo. Improving avocado margin dynamics and integration-related savings should provide additional support. Moreover, rising avocado consumption and growing retail penetration offer opportunities to expand market share. Nevertheless, persistent pricing pressures, integration costs and elevated debt remain concerns. The company's ability to execute operational improvements, generate stronger cash flow and realize acquisition synergies will be crucial to sustaining its recovery momentum.
How Are Other Agribusiness Players Driving a Recovery?
Corteva, Inc. (CTVA - Free Report) and Dole plc (DOLE - Free Report) are pursuing strategic initiatives to navigate industry challenges and strengthen profitability.
Corteva is focusing on innovation, operational efficiency and portfolio optimization to strengthen profitability amid persistent agricultural market challenges. Following the separation of its seed business, Vylor, Corteva is positioned as a more focused crop protection company, emphasizing differentiated products, biological solutions and improved cost competitiveness. Demand for newer crop protection technologies and ongoing productivity initiatives could support its recovery despite competitive pricing pressures, particularly in Latin America.
Dole is prioritizing operational resilience, portfolio optimization and financial flexibility to navigate a challenging fresh produce environment. Although higher fuel and shipping costs, unfavorable weather conditions and supply disruptions have pressured its Fresh Fruit operations, strength across its diversified fresh produce businesses continues to provide support. The company's recent divestiture of its Ecuadorian port business has strengthened its balance sheet, creating greater flexibility for strategic investments and debt reduction.
AVO’s Price Performance, Valuation & Estimates
Shares of Mission Produce have lost 7.7% in the last three months compared with the industry’s decline of 27%.
Image Source: Zacks Investment Research
From a valuation standpoint, AVO trades at a forward price-to-earnings ratio of 14.44X, above the industry’s average of 14.69X.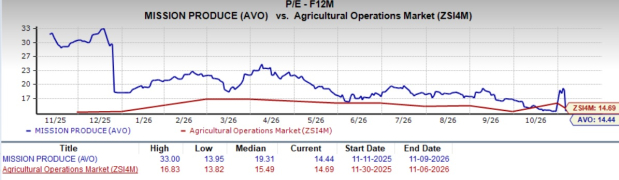
Image Source: Zacks Investment Research
The Zacks Consensus Estimate for AVO’s fiscal 2026 earnings suggests a year-over-year decline of 17.7%, while that for fiscal 2027 indicates growth of 33.8%. The company’s EPS estimates for fiscal 2026 and 2027 have remained stable in the past seven days.
Image Source: Zacks Investment Research
AVO stock currently carries a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.