We use cookies to understand how you use our site and to improve your experience.
This includes personalizing content and advertising.
By pressing "Accept All" or closing out of this banner, you consent to the use of all cookies and similar technologies and the sharing of information they collect with third parties.
You can reject marketing cookies by pressing "Deny Optional," but we still use essential, performance, and functional cookies.
In addition, whether you "Accept All," Deny Optional," click the X or otherwise continue to use the site, you accept our Privacy Policy and Terms of Service, revised from time to time.
You are being directed to ZacksTrade, a division of LBMZ Securities and licensed broker-dealer. ZacksTrade and Zacks.com are separate companies. The web link between the two companies is not a solicitation or offer to invest in a particular security or type of security. ZacksTrade does not endorse or adopt any particular investment strategy, any analyst opinion/rating/report or any approach to evaluating individual securities.
If you wish to go to ZacksTrade, click OK. If you do not, click Cancel.
HD Stock Falls 11.4% in a Month. Does the Pullback Offer Opportunity?
Read MoreHide Full Article
Key Takeaways
Home Depot shares fell 11.4% in four weeks, bringing its valuation closer to historical norms.
Home Depot's Q2 sales rose 5.7%, with digital sales up 11% and Pro outperforming DIY.
Home Depot faces soft traffic, weak housing turnover and cost pressures that constrain near-term upside.
The Home Depot, Inc. (HD - Free Report) shares have fallen 11.4% in the past four weeks, extending a 15.4% decline over the past 12 weeks. The retreat has brought the stock closer to the lower end of its recent valuation range.
The pullback improves the entry price, but the operating backdrop remains uneven. Pro demand, digital growth and broader category strength support the business, while soft traffic, weak housing turnover and cost pressure continue to limit near-term upside.
HD’s Pullback Brings Valuation Closer to Historical Norm
Home Depot trades at 18.93X forward 12-month earnings, below its five-year median of 22.09X and the S&P 500’s 19.84X multiple. The stock remains above the Zacks sub-industry’s 17.46X multiple, so the recent decline has not made HD unusually cheap relative to peers. Image Source: Zacks Investment Research
Shares are also down 27.6% over the past year and 13.8% year to date. That weakness has reset expectations, but the valuation still leaves room for further pressure if earnings growth or the housing backdrop disappoints.
HD Fundamentals Show Resilience Despite Soft Traffic
Second-quarter fiscal 2026 sales increased 5.7% year over year to $47.86 billion, while comparable sales rose 1.7%. Adjusted earnings increased 5.1% to $4.92 per share and topped the Zacks Consensus Estimate of $4.71.
The mix was less convincing beneath the headline growth. Comparable customer transactions declined 1%, while comparable average ticket increased 2.8%. Still, 13 of 16 merchandising departments posted positive comps, digital sales rose 11%, and Pro posted positive comps while outperforming DIY. Management expects total sales growth of 2.5-4.5% and comparable sales growth of flat to 2% for fiscal 2026.
Housing and Cost Pressures Keep the Risk Case Intact
Larger discretionary projects remain constrained by housing affordability and low turnover. Management said housing turnover has remained at historically low levels for four years, with no clear inflection point. That keeps demand tilted toward smaller repair and maintenance projects.
Margins also face pressure. Second-quarter gross margin benefited from a $685 million tariff refund, but higher fuel, energy and other product input costs are expected to offset that benefit over the year. Adjusted operating margin slipped 10 basis points to 14.7%, and fiscal 2026 adjusted operating margin is projected at 12.8-13%.
Peer Results Reinforce a Mixed Home-Improvement Backdrop
Lowe’s Companies, Inc. (LOW - Free Report) reported a 0.2% comparable-sales increase in its fiscal second quarter, supported by Pro, home services and online growth, while persistent DIY macro pressure remained a drag. The company also reduced its full-year comparable-sales outlook to flat.
Builders FirstSource, Inc. (BLDR - Free Report) faced a tougher housing environment. Second-quarter net sales fell 8.8% year over year, with the company citing lower housing starts and related headwinds. The contrast shows that repair-oriented demand can remain steadier than new-construction activity, but neither backdrop points to a broad housing recovery.
HD’s Signals Favor Patience After the Pullback
The 11.4% monthly decline has made Home Depot less expensive, while Pro momentum, digital growth and steady cash generation support the longer-term case. Yet soft traffic, constrained big-ticket demand and limited margin expansion keep the risk-reward balance from becoming clearly favorable on price weakness alone.
The Home Depot, Inc. Price, Consensus and EPS Surprise
HD currently carries a Zacks Rank #3 (Hold). It also has a VGM Score of B, Growth Score of B and Momentum Score of A, while its Value Score of C is less favorable. The combination points to solid growth and momentum characteristics, but the Zacks Rank suggests investors may prefer to wait for clearer earnings-estimate support before treating the pullback as a stronger buying signal.



 View the Zacks #1 Rank List


Image: Bigstock
HD Stock Falls 11.4% in a Month. Does the Pullback Offer Opportunity?
Key Takeaways
The Home Depot, Inc. (HD - Free Report) shares have fallen 11.4% in the past four weeks, extending a 15.4% decline over the past 12 weeks. The retreat has brought the stock closer to the lower end of its recent valuation range.
The pullback improves the entry price, but the operating backdrop remains uneven. Pro demand, digital growth and broader category strength support the business, while soft traffic, weak housing turnover and cost pressure continue to limit near-term upside.
HD’s Pullback Brings Valuation Closer to Historical Norm
Home Depot trades at 18.93X forward 12-month earnings, below its five-year median of 22.09X and the S&P 500’s 19.84X multiple. The stock remains above the Zacks sub-industry’s 17.46X multiple, so the recent decline has not made HD unusually cheap relative to peers.
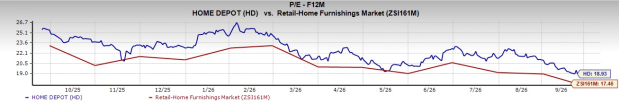
Image Source: Zacks Investment Research
Shares are also down 27.6% over the past year and 13.8% year to date. That weakness has reset expectations, but the valuation still leaves room for further pressure if earnings growth or the housing backdrop disappoints.
HD Fundamentals Show Resilience Despite Soft Traffic
Second-quarter fiscal 2026 sales increased 5.7% year over year to $47.86 billion, while comparable sales rose 1.7%. Adjusted earnings increased 5.1% to $4.92 per share and topped the Zacks Consensus Estimate of $4.71.
The mix was less convincing beneath the headline growth. Comparable customer transactions declined 1%, while comparable average ticket increased 2.8%. Still, 13 of 16 merchandising departments posted positive comps, digital sales rose 11%, and Pro posted positive comps while outperforming DIY. Management expects total sales growth of 2.5-4.5% and comparable sales growth of flat to 2% for fiscal 2026.
Housing and Cost Pressures Keep the Risk Case Intact
Larger discretionary projects remain constrained by housing affordability and low turnover. Management said housing turnover has remained at historically low levels for four years, with no clear inflection point. That keeps demand tilted toward smaller repair and maintenance projects.
Margins also face pressure. Second-quarter gross margin benefited from a $685 million tariff refund, but higher fuel, energy and other product input costs are expected to offset that benefit over the year. Adjusted operating margin slipped 10 basis points to 14.7%, and fiscal 2026 adjusted operating margin is projected at 12.8-13%.
Peer Results Reinforce a Mixed Home-Improvement Backdrop
Lowe’s Companies, Inc. (LOW - Free Report) reported a 0.2% comparable-sales increase in its fiscal second quarter, supported by Pro, home services and online growth, while persistent DIY macro pressure remained a drag. The company also reduced its full-year comparable-sales outlook to flat.
Builders FirstSource, Inc. (BLDR - Free Report) faced a tougher housing environment. Second-quarter net sales fell 8.8% year over year, with the company citing lower housing starts and related headwinds. The contrast shows that repair-oriented demand can remain steadier than new-construction activity, but neither backdrop points to a broad housing recovery.
HD’s Signals Favor Patience After the Pullback
The 11.4% monthly decline has made Home Depot less expensive, while Pro momentum, digital growth and steady cash generation support the longer-term case. Yet soft traffic, constrained big-ticket demand and limited margin expansion keep the risk-reward balance from becoming clearly favorable on price weakness alone.
The Home Depot, Inc. Price, Consensus and EPS Surprise
The Home Depot, Inc. price-consensus-eps-surprise-chart | The Home Depot, Inc. Quote
HD currently carries a Zacks Rank #3 (Hold). It also has a VGM Score of B, Growth Score of B and Momentum Score of A, while its Value Score of C is less favorable. The combination points to solid growth and momentum characteristics, but the Zacks Rank suggests investors may prefer to wait for clearer earnings-estimate support before treating the pullback as a stronger buying signal.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.